
An advisor for a mid-size self-insured employer came into its renewal with a familiar question: is there a better network for these employees? The plan had been with Cigna for years, and nothing was obviously broken. But the employer and the benefits consultant working the account wanted to go deeper. They wanted a real answer, built on complete information, not a guess based on last year’s discount percentage.
That question comes up at nearly every renewal, and it usually gets answered the same tired way: a carrier hands over a discount report, and the client either accepts it or shrugs and stays put. This case went a different route. Instead of one number from one source, the team pulled together cost intelligence, meaning negotiated rate data, claims history, and out-of-network patterns viewed together, and the result upends the assumption most advisors start with.
So Serif Health ran the numbers. Over 1,800 covered lives and more than 17,000 claim lines were repriced against four major reference networks, using actual negotiated rates instead of projected discounts. One network stood out clearly: Blue Card PPO.
But here is where the story gets interesting. If you only looked at the effective discount, you would have missed the entire opportunity. The discount barely moved, improving from 50.87% to 54.39%. On paper, most advisors would have called it a wash and stayed put.
But the real savings were not all in the discount.
Where the money actually was
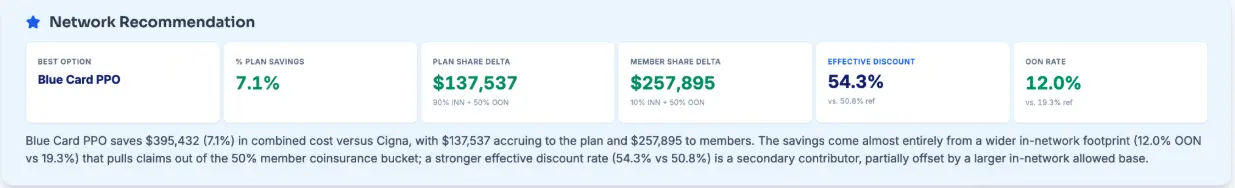
The full analysis found 7.1% in total plan savings, or roughly $395,000. That number breaks down in a way that matters to different people in the room.
- Of the $395,000, about $138,000 flowed to the employer. That is the figure a CFO cares about when comparing vendor options at renewal.
- The remaining $258,000 went to employees via lower shared costs. Lower member costs mean an easier open enrollment conversation and a better employee experience, not just a better balance sheet.
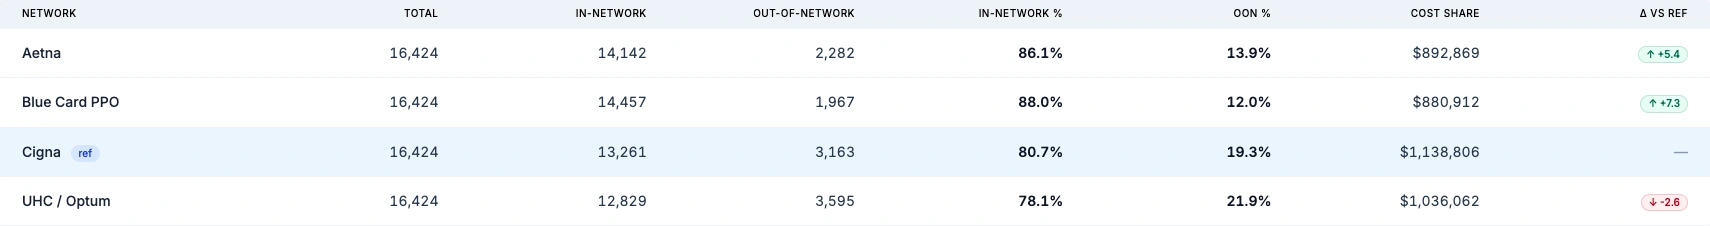
- Then there was a third number that almost got buried: $158,000 in additional savings from reduced out-of-network exposure.
Switching networks can backfire if members suddenly lose access to their existing providers but here the opposite happened. Out-of-network utilization dropped from 19% to 12% under Blue Card PPO, based on the plan’s actual claims history.
The network switch did not just cost less. It kept more members in network.
The Medicare cross check
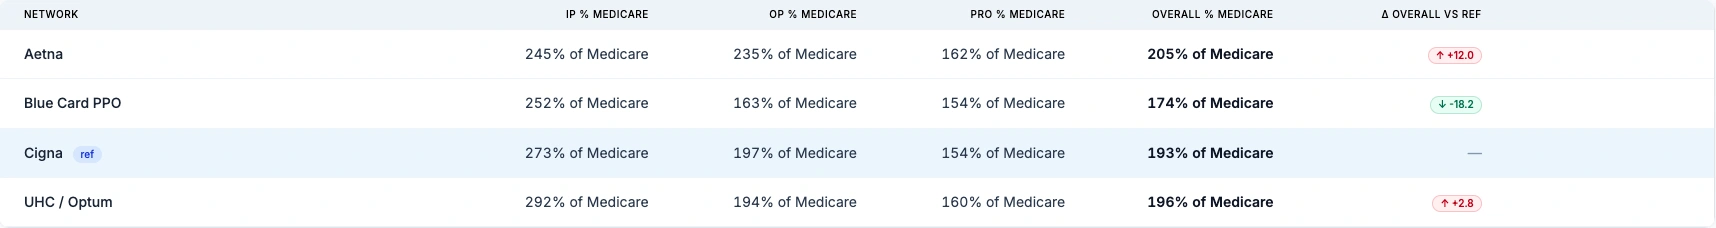
One more data point confirmed the recommendation: Blue Card PPO’s overall rates, expressed as a percentage of Medicare, came in 18% lower than Cigna’s. Raw rate comparisons can be noisy on their own. Normalizing against Medicare strips out some of that noise and gives a cleaner read on which network is genuinely cheaper across inpatient and outpatient care.
This is the type of insight that cost intelligence adds that a single discount figure cannot. It offers another independent data point, checked against the others, so the recommendation rests on more than one view of the same transaction.
What almost got missed
A four-point discount improvement is the kind of number that might get filed away as a mild win, not a reason to switch carriers. If the analysis had stopped at the discount comparison, this plan would likely have stayed on Cigna, left $395,000 on the table, and kept sending 19% of its claims out of network without ever knowing a better option existed.
Why this case matters beyond one employer
Every year, advisors sit across from clients weighing whether to switch networks. Too often, the answer gets built on a carrier’s own discount report, which will always flatter the carrier, and which reflects one number rather than the complete picture.
This case shows why that approach falls short. The effective discount told almost no story at all. The real signal came from cost intelligence: repricing every claim line against real negotiated rates, checking those rates against Medicare, and layering in actual utilization, including where members were going out of network and how that compared across options. Access to more complete information changed the decision entirely.
That is a fundamentally different kind of analysis. It requires claims data, current negotiated rates across multiple networks, and the ability to normalize for Medicare so the comparison holds up. It is not something you can do with a spreadsheet and a carrier’s summary sheet, because a single data point was never going to reveal what three data points, viewed together, made obvious.
The takeaway for advisors
Network selection must not rest on projected discount spread. It must rest on cost intelligence built from the real dollar difference, calculated from real claims repriced at real rates, with member disruption and Medicare benchmarks built into the picture.
For this plan, that meant $395,000 in identified savings, split fairly between employer and employees, with an added $158,000 from reduced out-of-network exposure and a clean 18% Medicare benchmark to back it up. None of it would have shown up in a discount comparison, because none of it lived in a single number.
The advisors who bring this kind of complete, cross-checked information into renewal season are not just presenting a recommendation. They are presenting evidence, and evidence is what turns a good guess into an informed decision.
Want to see what this kind of analysis would surface for one of your clients? Reach out to hello@serifhealth.com to learn how Serif’s Network Benchmarking module works.
To learn more about this strategy and approach, download our Cost Intelligence Playbook for Brokers and Advisors today.